Home projects in North Carolina: what gets financed and why
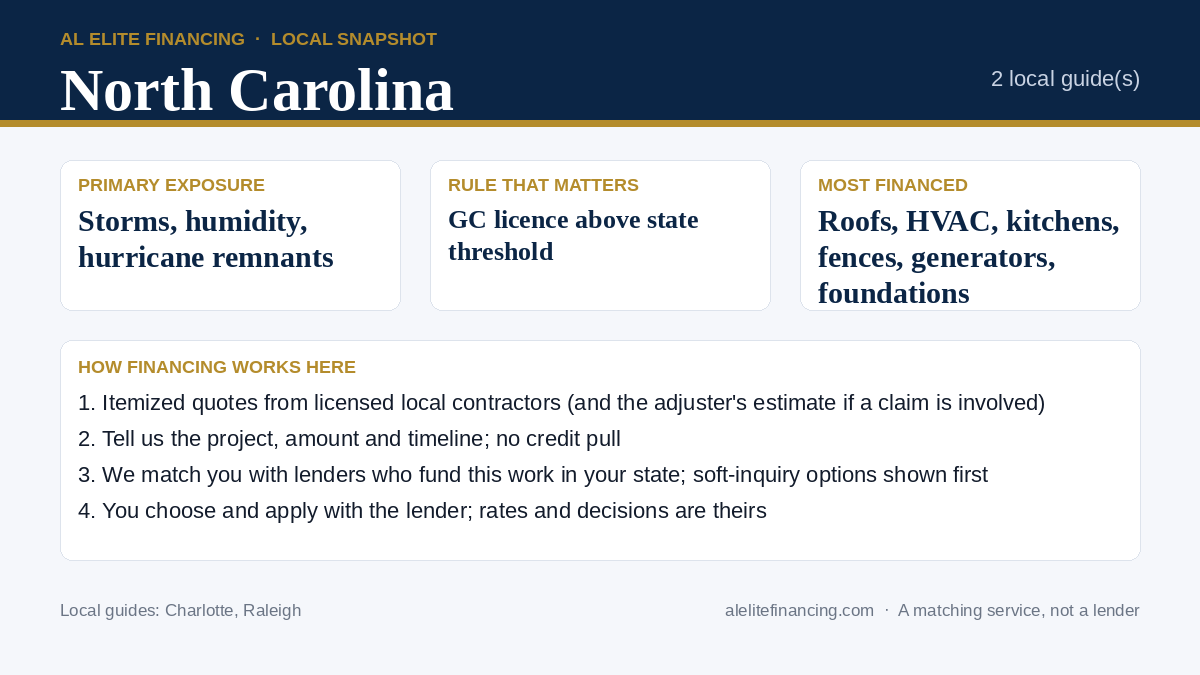
North Carolina stretches from the mountains to the coast, and its two largest metros, Charlotte and the Triangle, share humid summers, severe spring storms, occasional hail and tornadoes, hurricane remnants and winter ice. Both have grown so fast that first replacements of 1990s-era roofs, HVAC systems and water heaters are a wave of their own, while older neighborhoods need the renovation work that comes with a hot resale market. Crawlspace moisture is the state's signature home problem.
Roof financing, roof replacement financing and roof repair financing in North Carolina
Whether the search is for roof financing, roof replacement financing or roof repair financing in North Carolina, the loan products are the same: unsecured roof loans, contractor plans and home equity products. What changes is the amount: a repair is a short loan, a replacement after a claim is usually the deductible and uncovered items, and an age-driven replacement without a claim is the full job. The same lenders also fund HVAC, kitchens, fences, generators and the rest of the house across North Carolina; lender availability is set at the state level, so every town in North Carolina gets the same matching as the metros below.
Local guides for North Carolina
Charlotte, NC
Charlotte has been one of the fastest-growing metros in the Southeast for two decades, which means a very large stock of 1990s to 2010s homes now reaching their first roof, HVAC and water heater replacements, alongside older neighborhoods in Dilworth, Plaza Midwood and NoDa with renovation needs.
Raleigh, NC
The Triangle (Raleigh, Durham, Chapel Hill and the suburbs around them) combines a research-and-university economy with explosive residential growth in Cary, Apex, Holly Springs and Wake Forest.
North Carolina rules that affect your project and your financing
North Carolina requires a general contractor license for projects above the state threshold set by the Licensing Board for General Contractors, and licenses HVAC, plumbing and electrical contractors. Standard deductibles apply on most policies, with named-storm deductibles common near the coast.
Rebates, assistance and government-backed programs in North Carolina
Duke Energy and the electric cooperatives offer rebates on efficient HVAC, heat pumps and water heaters. Weatherization assistance runs through the NC Department of Environmental Quality. FHA Title I and USDA Section 504 apply for eligible homeowners. Links to the federal programs are in the sources at the end of this page.
Insurance claims in North Carolina: how the gap gets financed
North Carolina claims come from severe storms, hail, hurricane remnants and ice. Named-storm percentage deductibles are common near the coast and appear on some inland policies. Crawlspace moisture, the state's signature problem, is generally excluded as maintenance and financed in full.
When a claim pays most of a roof, siding or fence, the financing question is the gap: the deductible, depreciation held back until completion, and items the adjuster didn't allow. That is usually a smaller, shorter loan than the whole project. Our guide to roof financing after hail damage walks through the arithmetic, and the insurance and roof replacement guide covers policy language.
Financing options North Carolina homeowners use
- Unsecured personal loans. Days to fund, no lien, fixed rate. The most common route for roofs, HVAC, fences and generators.
- Contractor financing plans. A monthly figure next to the quote through the contractor's lender partner; ask whether promotional rates are deferred interest and whether the price is the same for cash.
- Home equity loans and HELOCs. Lower rates for large planned projects such as kitchens or whole-house siding, with weeks to close and a lien on the home.
- Government-backed programs. FHA Title I property improvement loans through HUD-approved lenders, FHA 203(k) for remodels folded into a mortgage, and USDA Section 504 repair loans and grants in eligible rural parts of North Carolina.
- Rebates and assistance. Utility rebates reduce what you finance on HVAC and insulation; weatherization assistance covers eligible households.
Financing by project type in North Carolina
Timing projects in North Carolina
Storm-driven work (roofs, siding, fences, gutters) peaks right after severe weather, when the best local contractors are booked for weeks and out-of-town crews arrive. Planned work (kitchens, bathrooms, windows, generators, water heater upgrades) is easiest to schedule in the shoulder seasons when crews have capacity and quotes are more competitive. Either way, arranging financing before you sign keeps the project on schedule: a pre-qualification that uses a soft credit inquiry costs nothing and tells you what you're likely to be offered before the deposit is due.
What lenders look at for North Carolina homeowners
Unsecured home improvement loans are approved on five things: your credit score and recent payment history, your income and how much of it already goes to debt, the amount requested, how long you've had credit, and a complete application. Reducing the amount (rebates, a smaller scope, a down payment), paying a card balance down before applying, having pay stubs or bank statements ready, and checking options with a soft pull before any hard inquiry improve offers at every lender. Home equity products add an appraisal and a required equity cushion, commonly 15% to 20% of the home's value.
How it works
- Get itemized quotes from licensed North Carolina contractors. If insurance is involved, get the adjuster's estimate so you know the gap.
- Tell us about the project. Amount, timeline, whether insurance is involved, your state. No credit pull.
- We match you with lenders who fund that type of work in North Carolina, and show which start with a soft inquiry.
- You choose and apply with the lender. Rates, terms and the decision are theirs.
For North Carolina contractors
Roofers, HVAC companies, remodelers, fence and foundation contractors across North Carolina can offer customer financing at the estimate (paid at completion, deductibles handled legally where claims are involved) and get matched with business lenders for equipment, working capital and factoring. See for contractors.
Home improvement financing in other states
- Texas
- Oklahoma
- Colorado
- Missouri
- Kansas
- Nebraska
- Indiana
- Minnesota
- Florida
- Tennessee
- Utah
- Arizona
- Georgia
- Illinois
- Ohio
- Pennsylvania
Frequently asked questions
Can I get roof financing anywhere in North Carolina?
Yes. Lender availability is set by state, so homeowners anywhere in North Carolina get the same matching, whether they're in Charlotte, Raleigh or a smaller town. Our local pages cover the metros we hear from most.
Which home projects can be financed in North Carolina?
Roofs, HVAC, kitchens, bathrooms, fences, generators, foundation repair, siding, windows, water heaters, plumbing, solar, decks and pools. Tell us the project and amount and we match you with lenders who fund that work in North Carolina.
Can North Carolina contractors offer financing to customers?
Yes. Licensed, insured North Carolina roofers, HVAC companies, remodelers and other trades can join our partner program to offer customer financing and get matched with business lenders. See for contractors.
Does AL Elite have offices in North Carolina?
AL Elite matches homeowners and contractors online and by phone across the United States.
Sources and further reading
Primary sources we rely on for this page. Program rules change, so check the source before you rely on a figure.